
 (509) 525-4744
 September 8th, 2026
You reached a settlement after your car accident. The number sounds like a relief. Then a quiet question sets in: when do you actually see the money, and why is the check smaller than the headline figure? Learning how accident settlements are paid out ahead of time saves a lot of surprise later.
The truth is that a settlement rarely lands in your bank account as one clean deposit. It moves through a few hands first, and several bills get paid along the way.
The path is more predictable than most people expect.
That trust account step is the piece that surprises people. The money passes through it so that every bill connected to your case gets paid correctly before you receive your share.
A settlement is meant to cover more than cash in your pocket. Several items are typically paid from it first:
Whatever is left after these items is your net recovery. A good attorney works to lower these amounts wherever possible so that more of the settlement reaches you.
Subrogation is one of the biggest reasons a settlement shrinks, and it catches many people off guard.
In plain terms, subrogation is the right of a company that paid your bills to be repaid from your settlement. If your health insurer covered your treatment after the crash, it can ask for that money back once the at-fault driver pays.
The same idea applies to medical liens, where a hospital or clinic treats you and files a claim to be paid from your recovery. These claims are sometimes larger than they should be, and some do not hold up when reviewed closely.
Our guide on how medical liens affect your settlement breaks down how they work and where they can be challenged.
This is where careful work pays off. Reviewing every bill, questioning inflated charges, and negotiating reductions can put thousands of dollars back into your pocket. We cover the wider picture in our guide on how medical bills are paid after a car accident.
This varies from case to case, so there is no single number. A few things affect the timeline:
Simple cases can wrap up in a few weeks after signing. Cases with several liens or disputed bills take longer, because those claims should be settled before the final check is cut. Rushing this step can leave a bill unpaid that comes back later.
Most vehicle accident settlements are paid as a lump sum, meaning one payment after the deductions are handled.
In some larger cases, part of the money is paid through a structured settlement instead. That means the money arrives in scheduled payments over time rather than all at once. Each approach has trade-offs around taxes, budgeting, and long-term needs. Which one fits depends on the size of the recovery and your situation, and it is worth talking through before you decide.
Why is my settlement check less than the amount we agreed on?
Attorney fees, case costs, medical bills, and any insurance reimbursement come out of the total first. What remains is your net payment.
Can medical liens be reduced?
Often, yes. Many liens are open to negotiation, and some contain charges that can be challenged. A close review can lower the amount owed.
Do I have to pay my health insurance back from my settlement?
Sometimes. If your health plan paid for accident-related care, it may seek repayment through subrogation. That amount can often be negotiated down.
Your settlement check goes to a trust account, the bills tied to your case are paid, your attorney’s fee and costs come out, and the balance goes to you. The more skillfully the liens and reimbursements are handled, the more of the money you keep.
If you were hurt in a crash in Hermiston or anywhere across Eastern Oregon, Eastern Washington, or Idaho, you do not have to sort out this process alone. Hess Injury Law works on a contingency basis from our local Hermiston office, and our team handles every lien and bill so your final payment is as high as it can fairly be.
A Hermiston personal injury lawyer can review your case for free. Contact our office to get started.
Disclaimer: The content of this blog is for informational purposes only and does not constitute legal advice. It should not be relied upon as a substitute for professional legal counsel.
Disclaimer: The content of this blog is for informational purposes only and does not constitute legal advice. It should not be relied upon as a substitute for professional legal counsel.
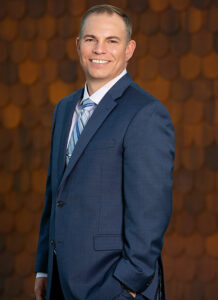
Peter J. Hess grew up in Walla Walla, Washington. He is a 1996 graduate of Walla Walla High School and a 2000 graduate of the University of Washington, with a B.A. in Business Administration/Information Systems.
Peter graduated from Willamette University College of Law, with honors, in 2007. While at Willamette, he was an Associate Editor of the Willamette Law Review, he was a Teacher’s Assistant for a Legal Research and Writing professor, and he worked as a Personal Injury Law Clerk at Swanson, Lathen, Alexander & McCann in Salem, Oregon. After graduation from Willamette, Peter began working here at Hess Injury Law. In 2012, he became a partner in the firm. He is licensed to practice law in both Washington and Oregon.